The initial compliance-review period is three months, subject to extensions. ANSA interprets the French six-month document requirement as applying to the certificate, not the approved merger terms. An older merger plan does not automatically need to be redone, and three months is not a guaranteed closing timetable.
Why a U.S. group should care about a French procedural deadline
A U.S. parent plans to consolidate two European subsidiaries. The group owns both businesses, management has approved the transaction and integration is scheduled. Yet an internal sign-off does not complete the European legal process.
Article L. 236-31 of the French Commercial Code addresses eligible French companies merging with eligible companies governed by another EU Member State’s law. U.S. ownership of the group does not itself prevent European subsidiaries from using that framework. A direct merger between a French company and a U.S.-incorporated company is not automatically covered by it.
This article concerns French corporate-law formalities, not U.S. merger filing rules or a timetable for antitrust clearance.
What “simplified” actually removes
For qualifying transactions, Article L. 236-11 of the French Commercial Code dispenses with specified shareholder approvals and reports. It does not dispense with cross-border scrutiny.
The French provisions distinguish pre-merger review under Article L. 236-42 of the French Commercial Code from final review under Article L. 236-43 of the French Commercial Code when the resulting company is registered in France.
| Stage | Purpose | Outcome |
|---|---|---|
| Pre-merger compliance review | Check the company’s preparatory formalities and, among other matters, potential abuse or fraud | Pre-merger certificate or reasoned refusal |
| Final legality review | Check the common approved terms and relevant employee participation arrangements | Approval or rejection of the operation |
The French greffier is the court registrar exercising these statutory review functions. The certificat de conformité is a pre-merger certificate, not evidence that the transaction has already become effective.
When does the French three-month clock start?
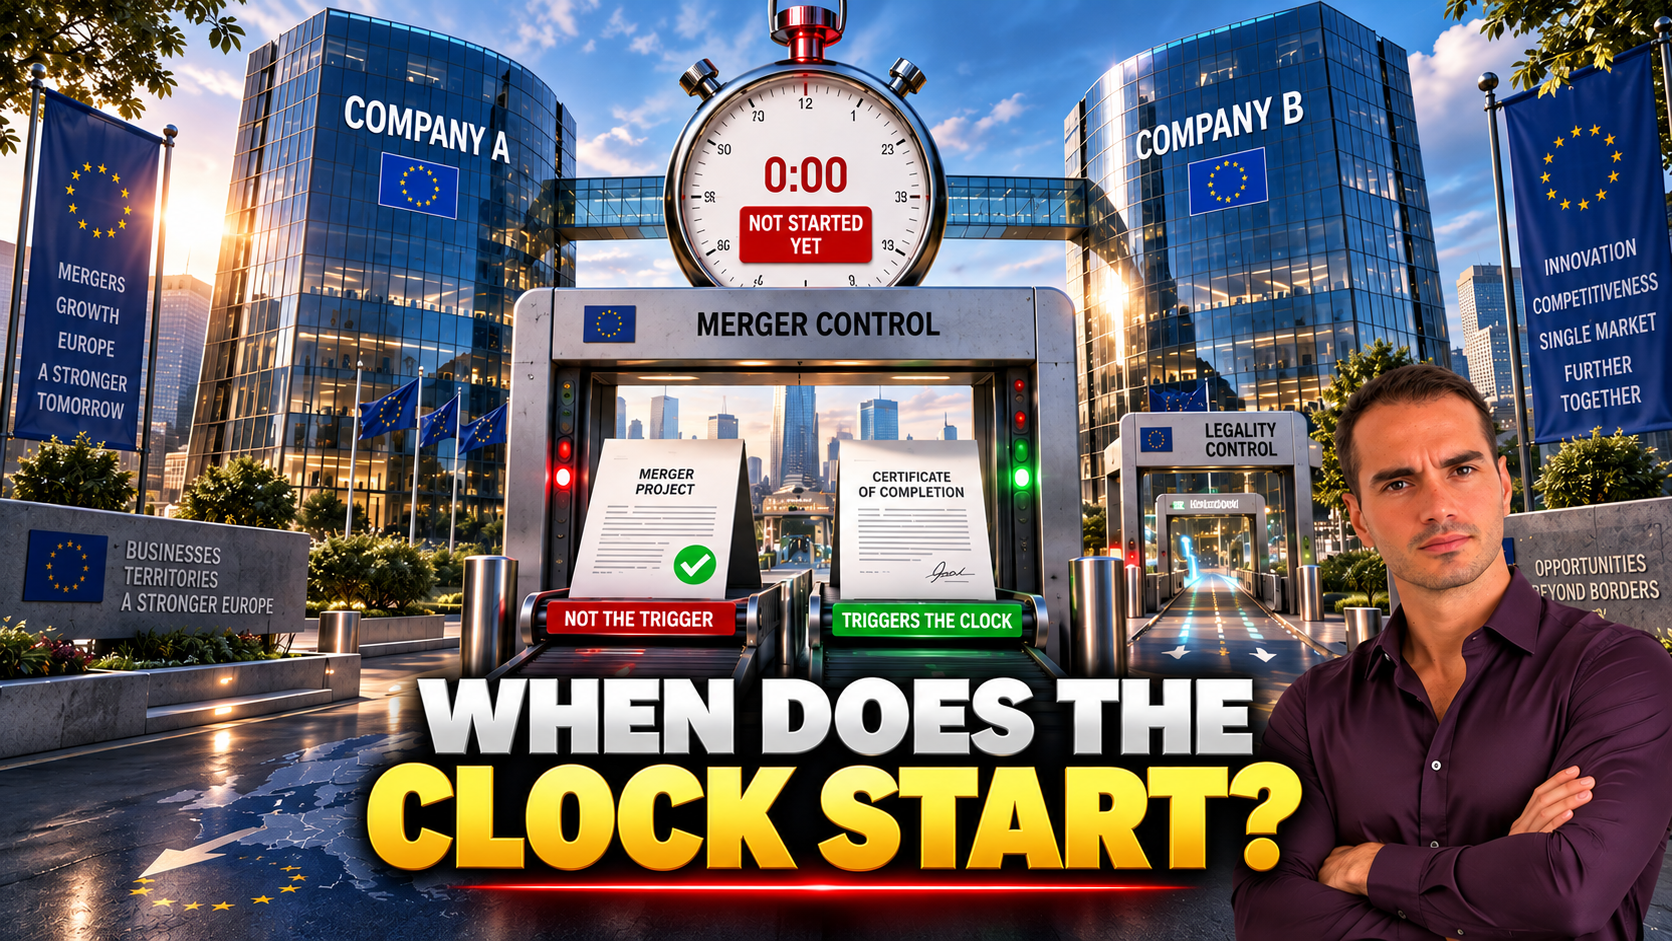
Article R. 236-30 of the French Commercial Code distinguishes receipt of the shareholders’ approval minutes from, where no meeting is required, the date the competent corporate body decides on the merger.
ANSA Legal Committee Opinion No. 26-039 of June 3, 2026 addresses the simplified case: the duly authorized directeur général’s formal record of realization starts the clock, rather than initial approval of the plan. In a French SA, authority is delegated by the board; a SAS president may also delegate that task.
ANSA provides professional interpretation, not a court ruling. Its full opinion is members-only; the account of its position here relies on EFL’s published report.
The regulation allows an extension of up to three months and, for complex cases, additional reasoned one-month extensions that can be renewed. There is no automatic six-month overall ceiling.
Where final scrutiny is conducted in France, Article R. 236-32 of the French Commercial Code provides a fifteen-day review period following receipt of all documents. That does not turn the transaction into a guaranteed “three months plus fifteen days” process.
The six-month rule concerns the certificate, not the merger plan
Article R. 236-31 of the French Commercial Code refers to a document less than six months old in the final-review file. Its drafting leaves room for confusion between the certificate and approved merger terms.
ANSA’s answer is the certificate. The historical basis is clear in Article 128(2) of Directive (EU) 2017/1132, as originally enacted: the six-month period ran from certificate issuance.
Consider an illustrative filing containing merger terms approved eight months earlier and a certificate issued two months earlier. The age of the merger terms does not, by itself, require renewed approval under this freshness requirement. Other requirements remain relevant, including whether the companies approved the same terms.
There is an important qualification. Directive (EU) 2019/2121 of November 27, 2019 replaced the relevant EU provision without retaining the six-month requirement and introduced certificate sharing through interconnected registers. The French regulatory wording reviewed for this article still contains six months.
Counsel should address that mismatch with the competent authorities. Neither a universal European six-month deadline nor an unqualified assumption that the French wording can be ignored is a sound basis for a closing schedule.
Does a timing mistake automatically invalidate the merger?
No. An incomplete or noncompliant file may require further information or regularization, and the registrar may refuse a certificate. French law treats the preliminary control as a requirement backed by nullity, but the rules on effectiveness qualify that exposure.
Article L. 236-44 of the French Commercial Code prohibits declaring a cross-border merger null after it has taken effect. For a merger into an existing company, it also limits the effective date: it cannot precede final legality review or the relevant authorities’ receipt of the certificate, or exceed the relevant financial year-end of the beneficiary company.
The executive’s internal record is therefore not a substitute for regulatory completion. The immediate commercial risk is a delayed integration or avoidable rework, not an automatic cancellation triggered by a calendar error.
What U.S. deal teams should put on the closing checklist
Start with the entity that survives and the jurisdictions of all participating companies. Then track the corporate decision, delegation, formal record, each certificate, cross-border transmission, final review and legal effectiveness separately.
Identify who owns each step and what document proves completion. French and destination-state counsel should agree on which authority applies which deadline. A French review period should not be inserted unchanged into another country’s process.
For finance and operations, the important distinction is between a target integration date and a legally available effective date. Moving banking, invoicing or operational responsibilities on the assumption that a certificate will arrive can create avoidable disruption if review is extended.
A coordinated legal function does not need to make the transaction slower. Its value is to prevent the group from committing resources to a date that the governing procedure cannot yet support.
Does full ownership remove cross-border merger scrutiny?
No. It may support simplified approvals and reporting, but it does not eliminate the relevant pre-merger and final reviews.
Is the French compliance review always completed within three months?
No. Three months is the initial period. The regulation permits extensions, including renewable monthly extensions in complex cases.
Is the executive’s record equivalent to legal closing?
No. Internal corporate documentation and legal effectiveness are distinct. The applicable controls and conditions must still be satisfied.
Is this the timetable for merging a U.S. company directly into a French company?
Not automatically. The framework discussed here concerns qualifying intra-EU mergers involving France. It is relevant to U.S. groups reorganizing their European subsidiaries.
Do these reviews replace other regulatory approvals?
No. They concern corporate-law merger scrutiny. Other applicable requirements must be analyzed separately rather than assumed to be covered by a pre-merger certificate.
The practical takeaway
A reliable closing schedule distinguishes the act that starts review, the document whose age matters and the event that makes the merger effective. Full ownership may simplify governance approvals; it does not make those three milestones interchangeable.