
That changed on January 1, 2026.
A new Belgian law imposes a general 10% tax on gains from financial assets, with a €10,000 annual exemption for 2026.
Entrepreneurs owning at least 20% of a company receive a much more favorable regime: the first €1 million of gain is exempt, followed by progressive rates of 1.25%, 2.5%, 5%, and 10%.
The most important feature for internationally mobile investors, however, may be Belgium’s immigration step-up.
When an individual becomes subject to Belgian personal income tax after moving to Belgium, the market value of financial assets on the first day of Belgian tax residence generally becomes their Belgian tax basis.
In practical terms, Belgium primarily taxes appreciation arising after immigration, rather than gains accumulated before the move.
Belgium’s Historical Advantage
For decades, Belgium stood out in Europe because capital gains realized by individuals in the normal management of private wealth were generally exempt.
The 2026 reform changes that philosophy.
Belgium now taxes future financial capital gains.
But the reform is not equivalent to adopting the tax burden found in neighboring France or Italy.
The New General 10% Regime
Beginning January 1, 2026, gains on financial assets realized in the normal management of private wealth generally fall within a new 10% tax regime.
For 2026, an individual receives a €10,000 annual exemption.
Belgium also created a separate regime for taxpayers holding a substantial interest in a company.
Founders Owning at Least 20% Receive a Preferential Schedule
An individual who owns at least 20% of the rights in the company whose shares are sold can benefit from a special regime.
The first €1 million of gain is exempt, subject to a five-year lookback rule for prior use of that exemption.
Above that amount, the rates are progressive:
- €0 to €1 million: 0%
- €1 million to €2.5 million: 1.25%
- €2.5 million to €5 million: 2.5%
- €5 million to €10 million: 5%
- above €10 million: 10% on the excess
Example: A €10 Million Gain Does Not Produce a €1 Million Tax Bill
Assume a founder owns more than 20% of a company and realizes a €10 million capital gain.
The Belgian calculation is:
First €1 million
Exempt. Tax: €0
€1 million to €2.5 million
€1.5 million × 1.25% = €18,750
€2.5 million to €5 million
€2.5 million × 2.5% = €62,500
€5 million to €10 million
€5 million × 5% = €250,000
Total tax: €331,250
The effective tax rate on the €10 million gain is therefore approximately 3.31%.
The Real Story: Belgium’s Immigration Step-Up
For internationally mobile founders, this is arguably the most consequential part of the reform.
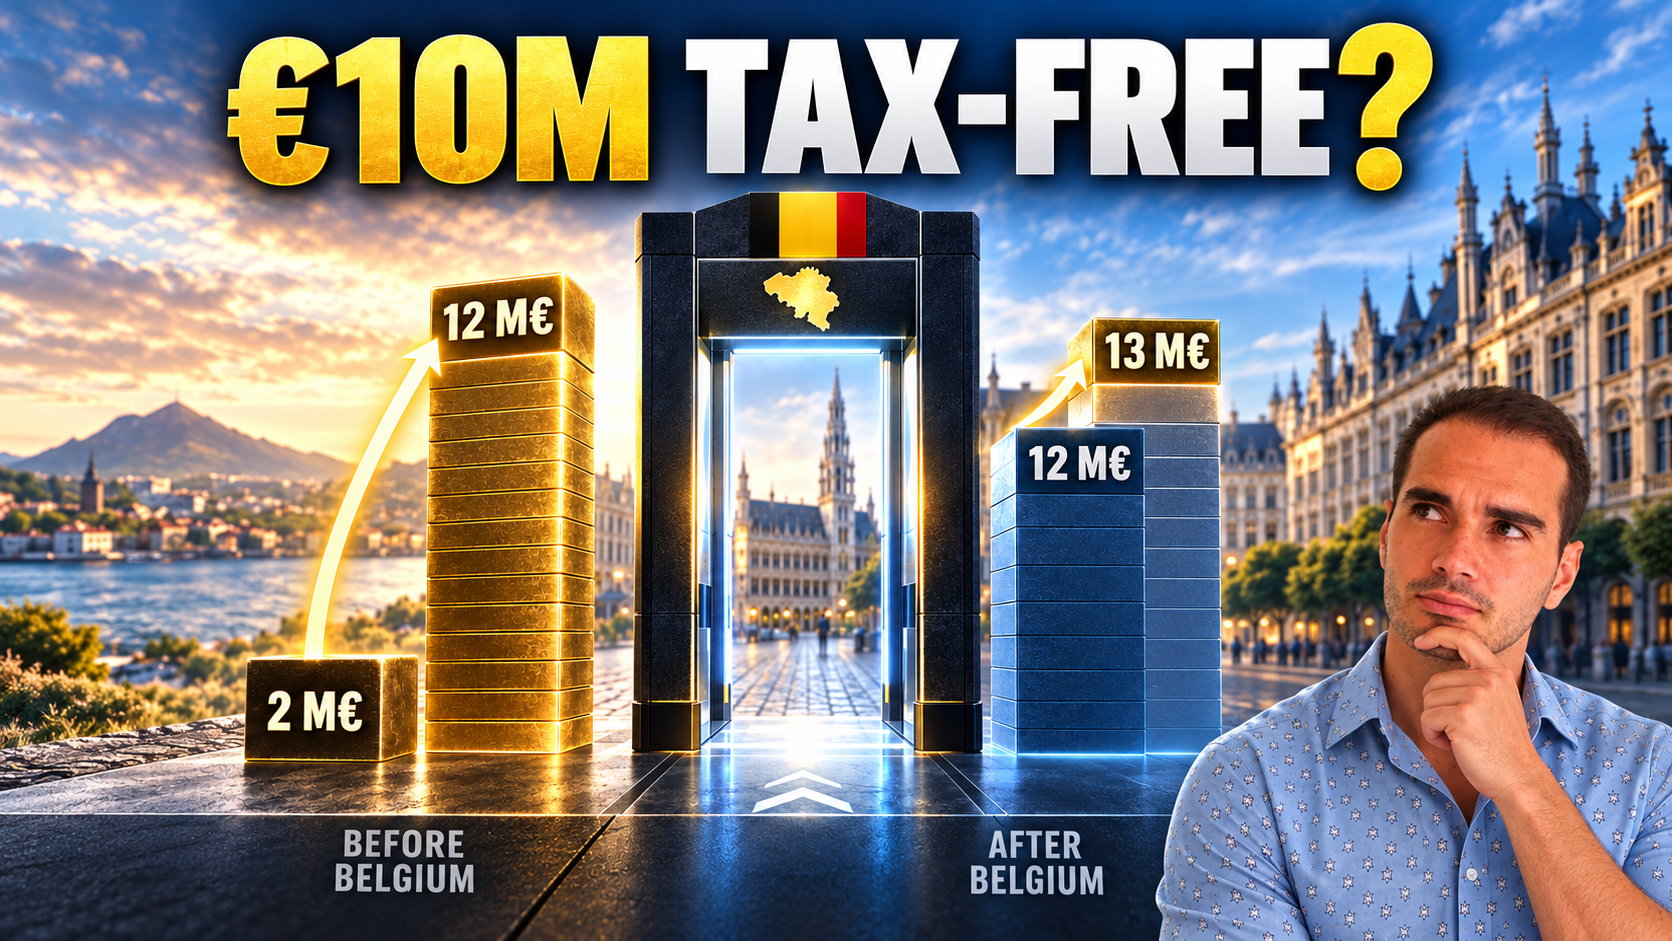
When an individual moves to Belgium and becomes subject to Belgian personal income tax, the market value of financial assets on the first day of Belgian residence generally becomes the assets’ Belgian acquisition value.
Consider a founder who originally purchased shares for €2 million.
When the founder moves to Belgium, the shares are worth €12 million.
If the shares are later sold for €13 million, Belgium generally does not calculate the gain from the original €2 million historical cost.
The Belgian gain is generally only €1 million, representing appreciation after immigration.
The €10 million of pre-immigration appreciation is effectively excluded from the Belgian capital-gains base.
That is the immigration step-up.
Why the Step-Up May Matter More Than the Tax Rate
A lower tax rate is valuable.
A reset tax basis can be even more valuable.
For a founder moving to Belgium with highly appreciated private-company shares, the step-up can materially reduce the amount of gain Belgium will ever tax.
That structure helps explain why Belgium may remain highly attractive to internationally mobile entrepreneurs even after introducing a capital gains tax.
How Does Belgium Compare With France and Italy?
Cross-country comparisons are never perfectly like-for-like because tax bases, exemptions, social charges, and special regimes differ.
Headline rates still provide useful context.
In 2026:
- Belgium: 10% under the general regime, after applicable exemptions
- Italy: 26% on many financial capital gains realized by individuals
- France: 31.4% under the standard PFU framework for ordinary securities gains
For a Belgian taxpayer selling a 20%+ substantial participation, the effective rate can be materially lower than the 10% general rate.
What Was Belgium Trying to Achieve?
The legislative materials describe the reform as part of fiscal consolidation and as implementation of the government’s proposed “solidarity contribution” on financial capital gains.
The philosophical shift is real.
Belgium is moving away from a system where normal private capital gains were largely outside income taxation.
At the same time, lawmakers preserved several mechanisms that limit the impact:
- a relatively low general rate;
- annual relief;
- preferential treatment of substantial shareholdings;
- protection of pre-2026 historical gains;
- and a step-up for new Belgian residents.
The result is better described as measured normalization than full convergence with neighboring tax systems.
What U.S. Founders Need to Know
For U.S. citizens and U.S. resident aliens, Belgium’s immigration step-up must be treated with particular caution.
The United States generally taxes U.S. citizens and resident aliens on worldwide income even when they live abroad.
A Belgian basis step-up therefore does not automatically reset the U.S. federal income-tax basis of the same shares.
An American founder moving to Belgium may consequently face a different gain calculation in Belgium and in the United States.
Separately, the U.S. expatriation tax is a different regime that generally concerns covered expatriates who relinquish U.S. citizenship or terminate certain long-term permanent-resident status. Simply moving to Belgium while remaining a U.S. citizen does not itself eliminate U.S. worldwide taxation.
What is Belgium’s capital gains tax rate in 2026?
The general rate is 10%, subject to exemptions and several special regimes.
What is the 2026 annual exemption?
The indexed general exemption for 2026 is €10,000.
What if I own at least 20% of my company?
The first €1 million of gain may be exempt under the substantial-participation regime, subject to the statutory five-year rule.
How much Belgian tax is due on a €10 million founder gain?
Under the 20%+ substantial-participation regime, the illustrative tax is €331,250, an effective rate of approximately 3.31%.
What is the Belgian immigration step-up?
It generally resets the Belgian tax basis of financial assets to market value when an individual becomes subject to Belgian personal income tax after moving to Belgium.
Does the Belgian step-up also reset my U.S. tax basis?
Not automatically. U.S. citizens and resident aliens remain generally taxable by the United States on worldwide income, and U.S. basis rules must be analyzed separately.
Conclusion
Belgium’s 2026 reform is a genuine change.
Private financial capital gains are no longer broadly tax-free.
But the reform did not eliminate Belgium’s competitive position.
For substantial shareholders, the progressive schedule can generate very low effective rates.
For new residents, the immigration step-up may be even more important because it generally excludes pre-arrival appreciation from the Belgian tax base.
For internationally mobile founders, the key question is which appreciation Belgium taxes, at what effective rate, and what tax the departure jurisdiction may impose before the move.